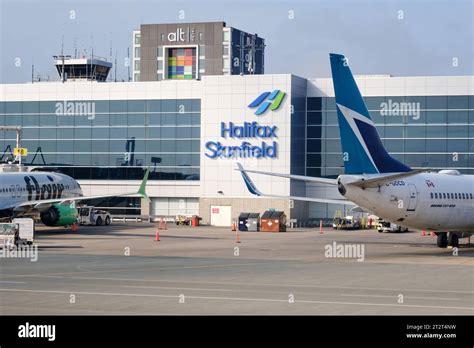
Halifax Stanfield International Airport spent the early weeks of 2026 celebrating numbers that would make far larger Canadian airports envious. Passenger traffic climbed to a record 4,140,668 travellers in 2025, a 4% increase over the 3,979,785 recorded a year earlier, and the international segment did something more impressive still. International passenger numbers surged from 441,053 to 526,352, a 19.3% jump that ran more than four times faster than the airport’s overall growth rate. For a mid-sized Atlantic Canadian gateway competing against the gravitational pull of Toronto, Montreal and Boston, those figures represented a genuine breakthrough in global relevance.
The celebrations came with a runway full of ambition attached. Halifax was preparing for a record 15 non-stop European services during the 2026 summer season, a schedule assembled around 57 year-round and seasonal routes that positioned the airport as one of the most internationally connected facilities in North America relative to its size. WestJet alone planned nine European destinations from Halifax, ranging from established favourites such as Dublin, Edinburgh and London Gatwick to newer bets on Copenhagen, Madrid, Lisbon, Barcelona, Amsterdam and Paris Charles de Gaulle. It was the kind of network map that small-city airports spend decades trying to build.
That momentum has now collided with a very different commercial reality. WestJet has removed Halifax (YHZ) to Copenhagen (CPH) and Halifax (YHZ) to Madrid (MAD) from its Summer 2027 schedule, less than a year after introducing both routes. Icelandair, meanwhile, will end its Halifax (YHZ) to Reykjavik (KEF) service after October 18, 2026. Three transatlantic city pairs, removed in a matter of months, from an airport that had just posted the best traffic year in its history.
A Record Year Built on International Growth
The contrast between Halifax’s traffic performance and its route losses is what makes this story worth examining closely, because the airport’s own data pointed firmly upward. The jump from 441,053 to 526,352 international passengers was not a modest statistical drift; it was a 19.3% expansion that outpaced the airport’s overall 4% growth by a wide margin. Domestic flying through Halifax was steady, but international travel was becoming the engine of the airport’s identity, and the 2026 schedule reflected a deliberate strategy of courting European carriers and expanding non-stop options.
WestJet’s 2026 European footprint from Halifax illustrated just how far that strategy had progressed. Copenhagen was scheduled to operate through September 27, Madrid through October 12, and alongside them sat Amsterdam, Barcelona, Dublin, Edinburgh, London Gatwick, Lisbon and Paris Charles de Gaulle. For a metropolitan area of roughly half a million people, that was an unusually broad collection of direct European options within a single seasonal timetable, a network that would have looked aspirational on paper five years earlier. The growth was not simply more Canadians passing through Halifax on their way somewhere else. International traffic had become an increasingly important structural component of the airport’s operation, and Halifax Stanfield had been actively and successfully expanding its European connectivity.
That makes the disappearance of three transatlantic links particularly striking, even though the cancellations do not erase the broader network that remains in place. Airports build route networks in layers, and the removal of a layer does not collapse the structure beneath it, but it does change the shape of what travellers can reach non-stop.
WestJet Reverses Its European Expansion in Halifax
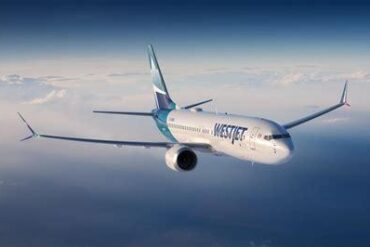
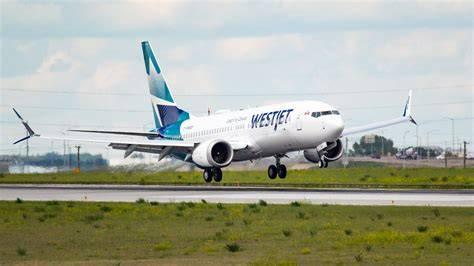
WestJet’s two Halifax cancellations concern routes that were barely established before being deleted from the following year’s schedule. Halifax to Copenhagen began on May 28, 2026, while Halifax to Madrid launched on May 15, with both planned as four-times-weekly summer services using Boeing 737 MAX 8 aircraft. These were not legacy routes with decades of brand recognition behind them. They were new-market experiments, launched into a crowded seasonal window and given roughly one summer to prove themselves.
The airline’s 2026 schedule had shown just how ambitious that expansion was, and for a mid-sized Canadian airport it created an unusually broad collection of direct European options within a single timetable. However, WestJet’s schedule changes made Halifax to Copenhagen and Halifax to Madrid unavailable for reservation by September 2026, and the airline has not included either route in its Summer 2027 plans. The two services are therefore being removed after their 2026 debut, placing them alongside Toronto (YYZ) to Glasgow (GLA) as part of a wider adjustment to WestJet’s European network.
Icelandair Is Leaving Halifax After October 2026
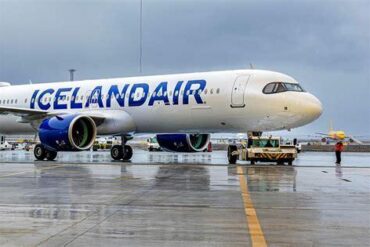
Icelandair’s Halifax operation follows a slightly different timeline, but it lands in the same place. Halifax Stanfield currently lists Reykjavik’s Keflavik International Airport (KEF) as a twice-weekly Icelandair service running from June 4 through October 18, 2026, which means the final scheduled flight falls on October 18. The route provided more than a direct connection to Iceland, because Keflavik functions as a useful connecting point within Icelandair’s broader network across Europe, giving Halifax travellers a one-stop path to Scandinavian and continental destinations that the airport otherwise could not reach non-stop.
Icelandair is dropping the Halifax to Reykjavik route and will not bring it back for the following summer, leaving the airport without a service that had become a recognised part of its seasonal European offering. Taken together, the Icelandair decision and WestJet’s two cancellations remove three transatlantic city pairs from Halifax’s future schedule in a relatively short period.
The changes do not mean Halifax is losing all of its European connectivity, since Air Canada, WestJet and Discover Airlines continue to serve European markets. However, they do demonstrate how quickly seasonal routes can disappear when airlines reassess their economics.
Fuel Costs Are Rewriting the Economics of Secondary Long-Haul Markets
The common factor identified in reporting around the cancellations is the cost of operating aircraft in an environment of stubbornly high aviation fuel prices. Airlines are increasingly scrutinising routes that are marginal or unprofitable, particularly as fuel expenses put pressure on the economics of services that do not consistently generate strong returns. When fuel is expensive, the break-even load factor rises, and a route that might have worked at a lower cost base can tip into unsustainable territory without any change in passenger demand.
That matters particularly for secondary airports, where airlines may have fewer opportunities to fill aircraft with high-value connecting passengers. A flight from Halifax to Copenhagen or Madrid has to generate enough revenue from its local market to justify the aircraft, crew, fuel and airport costs, whereas a large hub can combine connecting passengers from many origins with local demand. A traveller flying Halifax to Copenhagen via Toronto, Montreal or Amsterdam contributes revenue to a flight that would have operated anyway. A traveller on a dedicated Halifax non-stop has to justify the entire aircraft.
A route can therefore be useful to passengers while still proving difficult to make commercially sustainable. The situation is not unique to Halifax, but the airport’s experience illustrates the exposure of mid-sized cities to changes in airline network strategy, and the same fuel environment can leave major hubs relatively well protected while making a thinner seasonal route more vulnerable. In Halifax’s case, the speed of the reversals is especially visible because Copenhagen and Madrid had only just been introduced as new destinations for 2026.
Toronto Shows the Same Strategy Playing Out
WestJet is making a broadly similar adjustment at Toronto Pearson International Airport (YYZ), where its planned 2027 service to Glasgow (GLA) has been cancelled. Rather than maintaining both Scottish destinations, WestJet is consolidating its operation around Edinburgh (EDI), a decision described as a move toward the higher-yield market. The logic is consistent with the Halifax cuts: fewer, stronger routes rather than a scattered collection of thinner ones.
The change means Toronto to Glasgow will be left to Air Transat as the sole operator, with the airline using the Airbus A321LR on the route. Air Canada and WestJet, meanwhile, will continue serving Edinburgh, creating a clearer concentration of capacity around that market rather than splitting WestJet’s Scottish flying between two destinations. WestJet had returned to Toronto to Glasgow in 2026 with four weekly flights beginning May 15, so the cancellation also demonstrates how quickly a route can move from expansion to consolidation.
The decision does not indicate that transatlantic flying from Toronto is shrinking overall. Instead, it reflects an attempt to concentrate capacity where the airline expects stronger economics while leaving Air Transat to serve the Glasgow market.
Halifax Retains a Substantial European Network
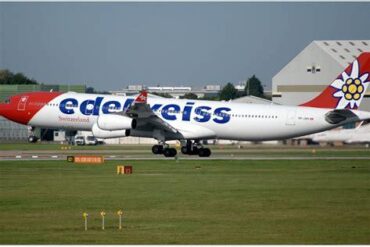
Despite the three losses, Halifax will retain a meaningful collection of European connections. Halifax Stanfield’s published schedule includes Air Canada’s year-round London Heathrow service, while WestJet continues to operate seasonal services to Amsterdam, Dublin, Edinburgh, London Gatwick, Lisbon and Paris Charles de Gaulle. Discover Airlines also serves Frankfurt (FRA) and Edelweiss Air serves Zurich (ZRH).
The remaining schedule shows why the cancellations should be viewed as a restructuring rather than the disappearance of Halifax’s international market. WestJet’s 2026 operation included four weekly flights to Dublin and three weekly flights to London Gatwick, while Edinburgh operated three times weekly. Those routes have more established histories than the two new destinations being removed from the 2027 programme, and there is also evidence that airlines continue to see opportunities around Halifax even while trimming individual routes. Air Canada added Halifax (YHZ) to Brussels (BRU) for summer 2026, while the airport continued to promote connections across Europe, North America and the Caribbean.
The airport’s record 2025 traffic therefore remains an important part of the story: demand is growing, but airlines are increasingly deciding where that demand can support profitable non-stop flying. Air Transat’s position on Toronto to Glasgow provides another example of how aircraft economics shape secondary long-haul markets. The airline operates 19 A321LR jets within an all-Airbus fleet, and the type is central to its strategy of using narrowbody aircraft on routes that might not justify a larger widebody.
That model is becoming particularly relevant in an environment where fuel costs are pressuring airlines across the industry. Air Transat’s 2026 financial performance provides a useful indication of the challenge: its second-quarter results were affected by a $95 million fuel and Cuba-related EBITDA shock. The episode shows why even leisure airlines built around efficient narrowbody aircraft remain exposed to sudden changes in fuel economics.
For Halifax, the immediate issue is therefore not a lack of passenger growth, but the gap between overall demand and the economics of individual routes. An airport can report record traffic while a particular city pair fails to produce the revenue an airline requires. Copenhagen, Madrid and Reykjavik are the latest examples, and their removal leaves Halifax’s remaining European services carrying greater importance as carriers enter the 2027 scheduling cycle.
What the Halifax Route Cuts Mean for Travellers and the Airport’s Next Chapter
The practical consequence for travellers is a network that becomes slightly more reliant on connecting through hub airports for Danish, Spanish and Icelandic destinations. Copenhagen and Madrid remain reachable from Halifax, but not non-stop, which adds hours and complexity to journeys that had only recently become direct. Reykjavik’s loss removes a convenient transatlantic stepping stone and narrows the one-stop options available to passengers heading deeper into Scandinavia.
The strategic consequence for Halifax Stanfield is more subtle. A record 4.14 million passengers, a 19.3% surge in international traffic and a 15-destination European summer schedule are achievements that took years of route development work to assemble, and they remain largely intact. What the three cancellations reveal is the fragility of the newest layer of that network. New seasonal routes serving mid-sized markets operate on narrow margins, and when fuel prices stay high and airlines grow more selective about secondary long-haul flying, the newest additions are the first to be reconsidered.
Halifax’s remaining carriers, from Air Canada’s year-round Heathrow link to WestJet’s Dublin, Edinburgh, Gatwick, Lisbon, Paris, Amsterdam and Barcelona services, plus Discover’s Frankfurt and Edelweiss’s Zurich connections, give the airport a European network that most cities of its size would envy. The question now is whether the demand that produced record traffic can be converted into the yields that keep the next generation of routes on the map. For an airport that has spent years proving it deserves international connectivity, the answer will determine whether 2026 stands as a peak or a platform.