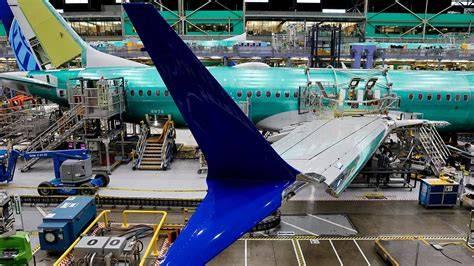
The headlines celebrating Boeing’s return to China tell a story of triumph, yet the operational scoreboard inside Chinese aviation tells a far more complicated tale. Boeing has clawed its way back into a backlog slot it lost nearly a decade ago, securing a framework commitment for 200 aircraft that US Trade Representative Jamieson Greer confirmed on September 21, 2026, is roughly 150 jets deep into formalization, with some 140 in what negotiators describe as a good state of negotiation. The expected mix blends domestic Boeing 737 MAX narrowbodies with international Boeing 787 widebodies, though Boeing CEO Kelly Ortberg has been careful to clarify that individual Chinese carriers will announce their own allocations on their own timelines rather than as one consolidated block. President Donald Trump has even floated the idea that the package could eventually scale toward 750 aircraft if phased implementation succeeds. It is a genuine diplomatic win, and it ends a purchasing freeze that began with a 300-jet package back in November 2017.
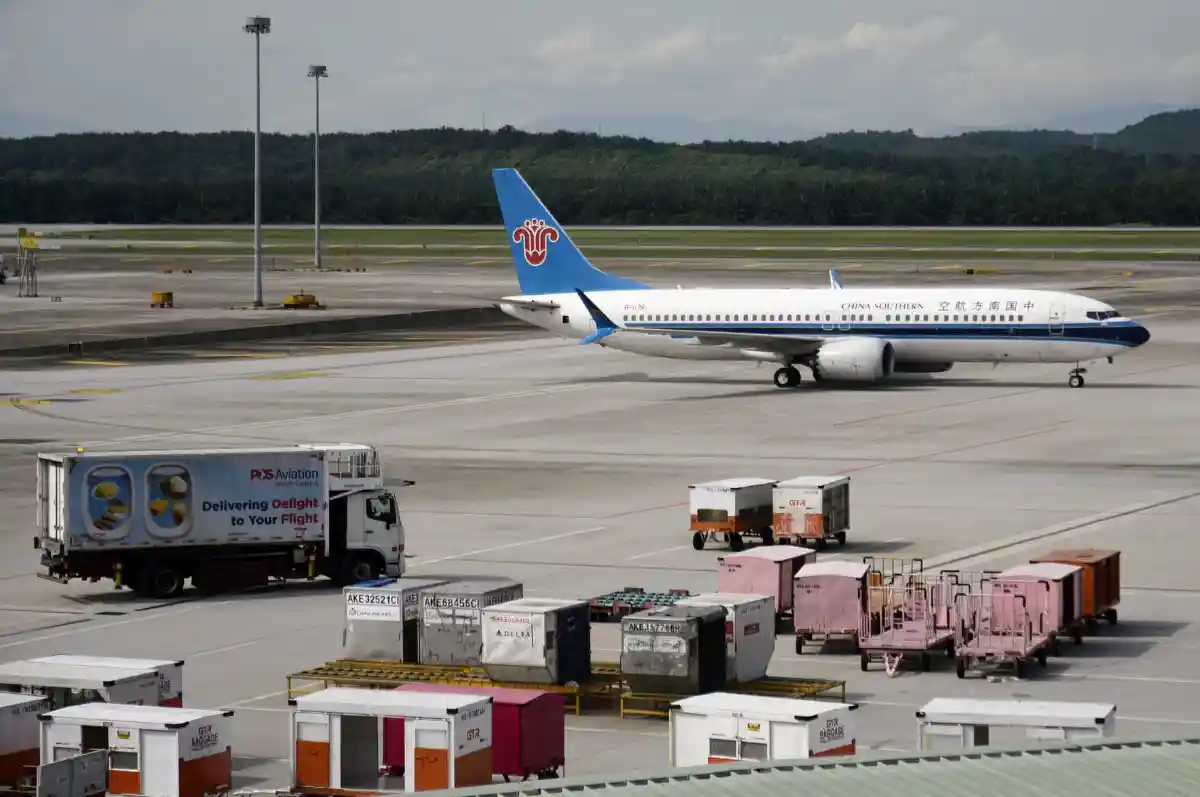
Yet beneath that political fanfare sits a procurement machine that moves nothing like the way Western aerospace executives imagine. China’s aircraft acquisitions are strictly centralized through state-owned entities, and turning a diplomatic framework into flying airframes requires navigating CAAC airworthiness certifications, pilot training cycles, currency settlement frameworks, and local industrial policy quotas. That ecosystem is precisely where Airbus holds a decisive and durable advantage, one that a single 200-jet tranche cannot dismantle. Airbus spent the years Boeing was absent embedding its narrowbody aircraft across state-owned fleets, and those aircraft are already flying, already financed, and already integrated into route planning that stretches years ahead. A commitment is a promise; a Tianjin-built A320neo rolling off the line is an asset. That distinction matters more than any ceremony in Washington or Beijing.
Why Airbus’s Tianjin Assembly Line Beats Boeing’s Export-Only Model
Airbus operates its Final Assembly Line Asia (FAL Asia) in Tianjin, and that facility is the single most important structural advantage in this contest. Chinese carriers can take delivery of A320neo and A321neo airframes assembled inside Chinese borders, paying in local currency while simultaneously satisfying state industrial manufacturing quotas that Beijing treats as a matter of national priority. Every aircraft that leaves Tianjin strengthens the case for Airbus with regulators, with provincial governments, and with the planners who decide which manufacturer’s jets appear in the next Five-Year Plan. That home-court positioning is not a marketing talking point; it is an operational reality with quarterly delivery numbers attached to it.
Boeing, by contrast, runs an export-only model from Washington state and South Carolina, which exposes Chinese airlines to foreign exchange volatility and cross-border tariff risk precisely during the moments when trade relations are most fragile. When tariffs spike and rhetoric escalates, Airbus keeps delivering from inside the country while Boeing’s jets sit waiting on the other side of the Pacific. To its credit, Boeing’s package incorporates critical engine supply guarantees from GE Aerospace to ensure operational stability, a recognition that even the aircraft itself is only one link in a long and politically exposed supply chain. Until central procurement agencies formally distribute delivery slots across Air China, China Eastern, and China Southern, Boeing remains locked inside a multistep conversion process while Airbus continues handing over factory-fresh aircraft without ever crossing a single international border.
Inside China’s State-Owned Procurement System
The mechanics of Chinese airline fleet procurement explain why headline jet counts flatter Boeing more than they should. Major acquisitions are governed centrally through state-owned entities before any individual airline assigns a tail number or files a flight schedule. The main mechanism runs through the China Aviation Supplies Holding Company (CASC), working alongside SASAC and the Civil Aviation Administration of China. CASC serves as the central purchasing agent, negotiating high-level framework agreements and then assigning specific delivery slots to state-owned carriers. Boeing is currently formalizing its 200-jet framework through exactly this channel, which means the commitment exists at the diplomatic layer rather than the fleet-planning layer.
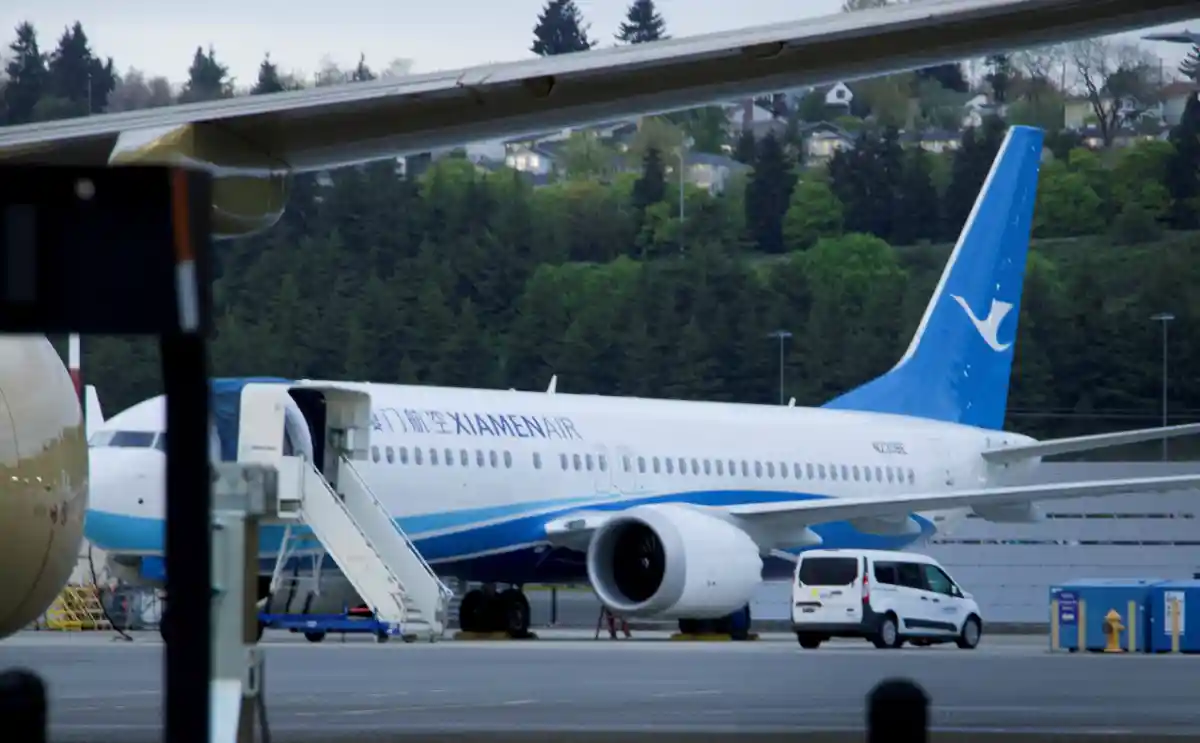
Airbus, meanwhile, has consistently locked in firm, carrier-specific orders over recent months. That includes 60 A320neo-family aircraft for Air China in late 2025 and 137 A320neo-family jets for China Southern and Xiamen Airlines in early 2026, according to coverage by AeroTime. Those are not frameworks awaiting distribution; they are binding contracts tied to named operators with defined delivery windows. That difference in order maturity is the whole story of Airbus’s commercial head start. Taking delivery through CASC means aligning factory production lines with CAAC airworthiness clearances and airline pilot training cycles, and Airbus’s pipeline is already woven into Chinese fleet planning while Boeing must still walk a multistep path from diplomatic commitment to active, revenue-generating airframes.
Timelines Belong To The Airlines, Not The Negotiators
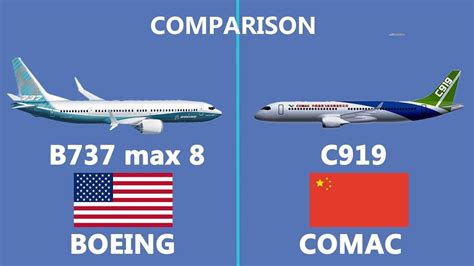
Converting political goodwill into tangible deliveries is Boeing’s toughest operational hurdle, and it is a hurdle no trade official can clear on the manufacturer’s behalf. Airline fleet managers must justify every aircraft addition against route network demand, crew availability, and long-term operating costs, and those calculations take time. Kelly Ortberg acknowledged this reality directly when discussing the 200-jet commitment, noting that individual Chinese airlines will announce allocations and models on their own schedules. Aviation trade observers add another layer: Chinese carriers are carefully balancing narrowbody intake between Western imports and the domestic Comac C919, the homegrown answer to Western narrowbody platforms. As a result, Boeing’s order book will fill gradually as carriers finalize individual financing and delivery schedules with CASC, and any carrier can slow-walk its portion without ever formally canceling anything.
Trade officials see the arrangement as a critical step toward stabilizing American aerospace exports, and Greer’s confirmation that roughly 150 jets are moving through formalization with 140 in good standing gives the deal real momentum. Trump’s suggestion that the agreement could eventually scale toward 750 aircraft offers an even more ambitious horizon, but analysts caution that such expansion depends on uninterrupted supply chains and stable trade relations sustained across multiple years. That conditionality is the quiet weakness buried inside the announcement, because a framework that can expand with stability can also contract with instability. The airlines themselves hold the pacing, and they will move only as fast as their own network economics and state directives allow.
The Third Challenger Reshaping The Duopoly
The commercial airframe contest between Seattle and Toulouse is rapidly evolving into a complex triopoly as COMAC matures. Founded in 2008, the manufacturer found early success with the C909 before bringing the C919 to market in 2023. Crucially, COMAC’s state backing shields it from the ordinary pressures of a free market, and operating inside the world’s most rapidly expanding domestic aviation market gives it an enormous runway to scale. While Airbus and Boeing compete for high-yield long-haul and trunk routes, Chinese state-owned carriers are increasingly turning to the C919 to build internal narrowbody capacity, and that substitution directly caps the long-term market share available to Western manufacturers.
The scale of that domestic pivot is difficult to overstate. Major domestic airlines including Air China, China Eastern, and China Southern have each signed 100-jet commitments for the C919, which means a substantial slice of future Chinese narrowbody demand is effectively reserved before Boeing or Airbus ever enters the negotiation room. Airbus anticipated this strategic shift more than a decade ago when it built the first Final Assembly Line in Tianjin, aligning its business model directly with Beijing’s industrial planning targets and securing a home-court advantage that compounds every year. Boeing’s 200-jet framework, impressive as it is, must now compete for a pool of imported narrowbody delivery slots that is narrowing rather than widening, and that structural math constrains the upside no matter how well the diplomacy goes.
Trade Volatility, White Tails, And The Risks That Could Stall Deliveries
Despite the positive momentum around Boeing’s framework, major operational and geopolitical risks could delay or derail deliveries before a single additional airframe reaches Chinese soil. The biggest vulnerability is trade policy instability and potential tariff fluctuations, because commercial jetliner purchases function as high-profile diplomatic bargaining chips. Any sudden escalation in transpacific trade disputes could prompt central Chinese regulators to pause aircraft import approvals or defer delivery acceptances, and no contract clause fully protects against a decision made at the level of state policy.
A second critical hurdle involves the re-integration of stored 737 MAX airframes, often called white tails, built during the multi-year delivery freeze. Re-commissioning those jets demands extensive engineering inspections, CAAC airworthiness sign-offs, and flight crew recertification, and for Chinese fleet managers, accepting an older-build stored airframe carries distinct maintenance and scheduling challenges compared with receiving a brand-new A320neo straight off the Tianjin line. Engine and component supply bottlenecks add a third risk, with assembly line slowdowns potentially affecting global delivery slots, though supply guarantees secured through GE Aerospace are intended to blunt that exposure. Bilateral discussions through the US-China Board of Trade remain the primary mitigation channel, and ongoing alignment with Chinese aviation regulators continues, but none of these measures eliminates the underlying uncertainty.
What Actually Counts As A Boeing Win In East Asia
Boeing’s true progress in East Asia will not be measured in preliminary memorandum signatures or celebratory press conferences. The key metric is the registration of actual delivery slots on airline balance sheets, which requires state carriers to convert allocations into binding, noncancelable contract lines with assigned serial numbers. Until that conversion happens carrier by carrier, the order framework remains vulnerable to broader geopolitical shifts, and the gap between announcement and delivery can stretch across years. That is why the 200-jet package is best understood as an incremental step in a longer market recovery rather than an overnight reversal of competitive position.
Airbus’s lead in China, reinforced by its Tianjin assembly line, RMB currency settlement frameworks, and massive firm narrowbody order book spread across state-owned carriers, remains formidable by any measure. Boeing will benefit as Chinese airlines formalize commitments to support domestic route growth and international fleet renewal, and the end of the decade-long freeze is genuinely consequential for its global backlog. Yet as COMAC continues scaling C919 production for major Chinese carriers, both Western giants will increasingly find themselves competing for a more tightly regulated pool of imported widebody and narrowbody delivery slots. Boeing has taken one small, important step back into the world’s second-largest aviation market, but Airbus is still the manufacturer whose aircraft China is accepting today.